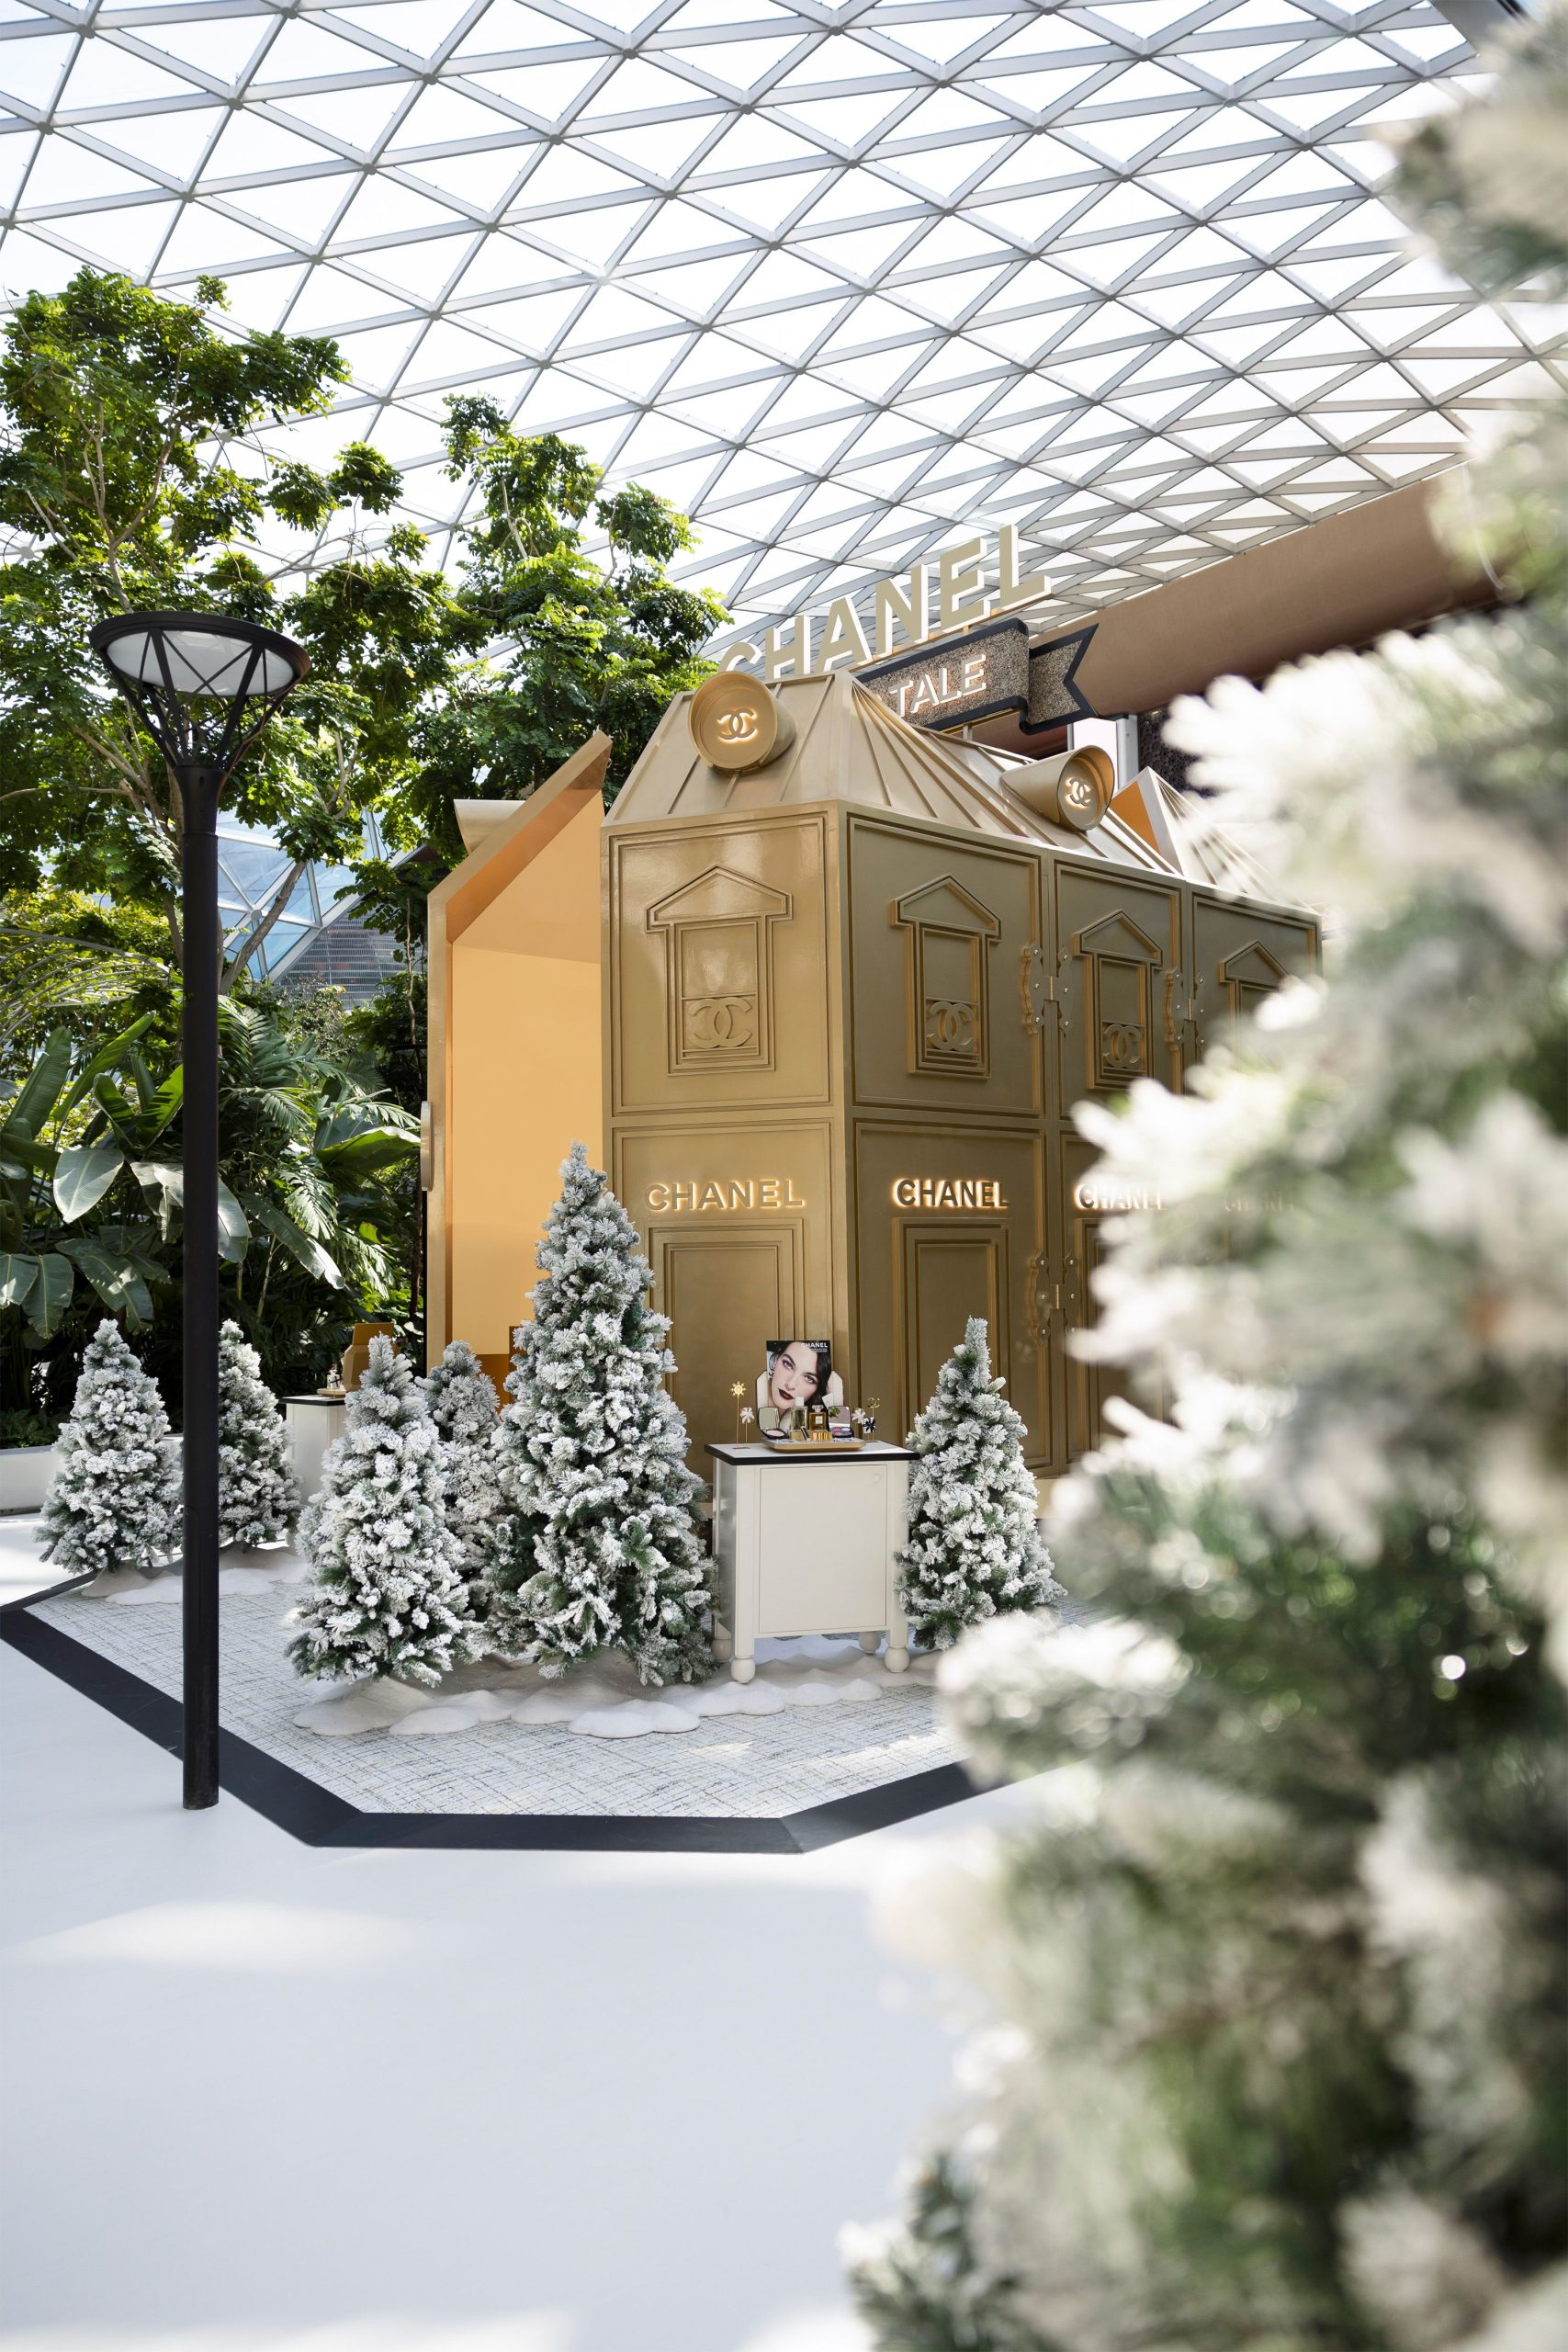
With global travel retail sales falling, brands and retailers are rethinking everything from product mix to presentation. With foot traffic rising, will shoppers return?With global travel retail sales falling, brands and retailers are rethinking everything from product mix to presentation. With foot traffic rising, will shoppers return?

More people than ever are traveling, but getting them to shop is proving harder. For beauty, one of travel retail’s biggest categories, recovery remains elusive.
Spanning airport duty-free stores, downtown duty-free shopping destinations, airlines and cruise ships, global travel retail is a vital sales and brand-building platform for beauty, offering access to millions of international travelers. Fragrance dominates sales in Western markets, while skincare has traditionally driven demand in North Asia, particularly among Chinese shoppers. In the Middle East, luxury fragrance and gifting are major draws. Beauty accounted for the largest share of the $76 billion global duty-free and travel retail market in 2025, at 32.2%, according to Generation Research.
Yet the traditional model, built around duty-free savings and access to a captive audience, is under pressure. Travelers are returning in record numbers, but spending is failing to keep pace. According to consulting firm Oliver Wyman, travel retail’s inability to keep pace with passenger growth has cost the industry around $5 billion since 2023 as increasingly informed consumers arrive at airports with more choice and fewer reasons to assume duty-free offers the best value.

Global travel retail sales of fragrance, skincare and makeup fell 5.6% to $13.8 billion in the first half of 2026, according to Generation Research, as the market changes.
The picture varies considerably by region. Asia-Pacific, historically the industry’s largest beauty travel retail market, remains the biggest drag on growth, with sales down 12.1% in the first half of 2026, according to Generation Research. Much of the weakness stems from Mainland China, where recent changes in airport retail concessionaires have disrupted sales. Longer term, the crackdown on daigou (or gray market) resellers, increased competition from domestic retailers and repatriation of Chinese beauty spending have undermined the traditional duty-free model. With Asia-Pacific accounting for more than 60% of global beauty travel retail sales, China’s difficulties have an outsized impact on the wider industry.

Elsewhere, the growth map is shifting. Europe and the Americas recorded sales increases of 8.9% and 9.8%, respectively, while the Middle East and Africa, one of the industry’s strongest-performing regions in recent years, slipped into decline, with sales falling 3.9% amid travel disruption in the Gulf from the US-Iran conflict.
“What is changing most is not only where travelers come from, but how they shop,” Hoffman says. “Today’s beauty consumer is more informed, more digital and more selective. Rather than focusing on nationality, we need to focus on understanding different traveler missions, preferences and spending occasions.”
Millennial and Gen Z shoppers, meanwhile, are becoming more important to travel retail. They account for 61% of global airline travel spending, a share expected to approach 80% by 2035, according to Oliver Wyman’s Global Travel Retail Pulse report released in September. The research also found that 49% of Gen Z travelers purchase immediately after discovering a new product in travel retail, compared with just 35% of baby boomers. But their shopping habits are very different from those of previous generations.
Technology, social media and AI have fundamentally changed how travelers discover brands, assess value and compare prices, often long before they reach the airport. According to new research released in October by consultancy Kearney for the Tax Free World Association (TFWA), 64% of surveyed travelers who used AI or social media to research travel retail walked past airport shops without purchasing. Meanwhile, 49% of respondents questioned whether duty-free prices were attractive.

How can an industry with access to growing passenger numbers be losing beauty sales? For Felipe Grant, Puig’s global travel retail president, the distinction is simple: “Passengers are not shoppers. They have to be converted into shoppers.”
For decades, the industry’s model was largely transactional — attract travelers with duty-free savings, stock established prestige brands, and rely on passenger volume to drive sales. As that model loses its pull, retailers and brands are rethinking how to turn travelers into shoppers.
At Gebr. Heinemann, the response is a more experience-led, data-informed approach, combining tailored assortments, exclusives and personalized services. “We believe the future growth of beauty in travel retail will come less from passenger volume alone and more from delivering greater relevance and value to every traveler,” says Hoffmann.
Not every operator is experiencing the same disconnect. Qatar Duty Free (QDF), which operates within the integrated Qatar Airways and Hamad International Airport ecosystem, says its beauty sales have consistently outgrown passenger traffic. But even there, the traditional duty-free proposition is being challenged.

Having prestige brands on well-merchandised shelves is no longer sufficient, says Thabet Musleh, Qatar Airways’s chief retail and hospitality officer. Instead, QDF is investing in bespoke experiences and activations that give passengers a reason to stop, explore and purchase.
“The more thought, care and creativity we put into curating that experience, the greater customer satisfaction and sales we inevitably get back,” says Musleh.
How fragrance became the center of the story
Fragrance is emerging as one of travel retail beauty’s most resilient categories, shaping how retailers attract and engage shoppers. Particularly well-suited for physical discovery, sampling and personalization, it offers a blueprint for how the wider beauty sector might reconnect with consumers.
According to Generation Research, fragrance was the only one of the three major beauty subcategories to grow in the first half of 2026, with sales rising 5.9% year-on-year, while skincare and makeup contracted. Fragrance’s share of global beauty travel retail sales rose from 35.7% to 40.1%. At QDF, niche fragrance sales grew 35% year-on-year, the retailer said, as travelers sought more complex, individual, and experimental scents.

The shift is already influencing how retailers allocate space and investment. At Gebr. Heinemann, fragrance is becoming the focal point of the beauty offer. “At locations such as Istanbul, Antalya or Keflavík, fragrance often acts as the anchor that draws travelers into the beauty area before they explore adjacent categories,” says Gebr. Heinemann’s Hoffmann.
Rather than simply expanding shelf space, Heinemann is investing in environments that encourage discovery and experimentation, including a dedicated niche fragrance area in Jeddah and an olfactive table in Keflavík. The objective is to use fragrance’s appeal to generate engagement across the wider beauty category.
The changing fragrance consumer is also creating opportunities for brands beyond traditional luxury perfume houses. Sol de Janeiro, which entered travel retail in 2023, has evolved from a bodycare business into a scent-led beauty brand, with fragrance central to its customer engagement strategy.
“Fragrance has taken such a big place in our customers’ hearts,” says the brand’s CEO Jordan Saxemard. “We started only 11 years ago, with bodycare and haircare, and with Brazilian Bum Bum Cream. That cream inspired our first scent, Cheirosa 62, which went on to create this beautiful phenomenon in fragrance.”
For luxury fragrance players, meanwhile, exclusivity is becoming an important tool. Puig’s airport-exclusive pre-launch of Carolina Herrera’s La Bomba last summer illustrates how travel retail can generate anticipation before a product reaches the domestic market.
“This was before the domestic market launch and without mainstream media,” says Puig’s Felipe Grant. “There was a sense of scarcity.” The launch created momentum ahead of wider distribution, demonstrating the potential for airports to play a more influential role in the product discovery journey.
Traveling beyond the discount
If shoppers can buy the same beauty products at Sephora, through TikTok Shop or directly from brands, what can airport retailers offer that they cannot find elsewhere?
For Australian beauty retailer Mecca, the answer lies in bringing its specialist retail model into an environment traditionally dominated by duty-free operators. Its recent debut at Sydney International Airport, in partnership with Gebr. Heinemann, marks a different approach to airport beauty — one built around discovery, curated brands and personalized service.
“We knew we couldn’t simply take a traditional Mecca store and put it into an airport. We’ve had to think about the traveler mindset and design the experience around that — how people discover products, how much time they have, and what they might actually want from beauty before a flight,” says Mecca chief operating officer Ian Burl.
The concept includes a Beauty Lounge, a travel-specific Mini Mart and services tailored to the pre-flight journey, alongside an assortment spanning Rhode, Summer Fridays, Diptyque, Byredo and Emma Lewisham. For Mecca, it is an opportunity to introduce its brand and retail experience to international travelers, while testing how its domestic model translates into the airport environment.

“Travelers expect novelty, whether through emerging brands, airport exclusives, locally relevant products or continuously refreshed collections that give them a reason to return,” says Pierre-Alexandre Koch, partner at Oliver Wyman.
Yet price remains a part of travel retail’s appeal. Despite growing expectations around exclusivity, discovery and experience, Oliver Wyman found that travelers expect airport prices to be around 18% below domestic retail. The challenge is to deliver those experiences and exclusivity without losing sight of duty-free’s traditional value proposition.
Established operators are adapting accordingly. At Gebr. Heinemann, the focus is on creating experiences and offers that cannot easily be replicated elsewhere, from personalized services to travel retail exclusives. Recent examples include Tılsım, a fragrance created by Tiziana Terenzi exclusively for Heinemann’s joint venture partner ATÜ Duty Free.
“What makes airport beauty unique is the combination of convenience, inspiration, and exclusivity,” says Hoffmann. “Travel creates a different mindset. People are often more open to discovery, more willing to treat themselves and more receptive to new brands, products and experiences than in their everyday routine.”
For QDF, creating this point of difference means working with brand partners on bespoke activations rather than replicating campaigns across airports. Its recent Charlotte Tilbury Star Confidence holiday campaign offers a compelling example of how this approach can translate into sales.

Informed by passenger data that identified make-up’s potential for gifting during the 2025 festive season, QDF partnered with Charlotte Tilbury on a terminal-wide holiday campaign at Hamad International Airport, extending across Qatar Airways flights, digital screens and an interactive pop-up. Travelers could try a 360-degree Glam Cam, personalize gifts with engraving, and shop airport-exclusive holiday sets, with a limited-edition gift offered on purchases over QAR 400 (about $110).
“The excitement started before passengers reached the pop-up, with app notifications, in-flight entertainment, in-airport displays, and bespoke content from Charlotte on social building hype and anticipation of what passengers would soon discover,” QDF’s Musleh explains. “Social interaction was also key to the concept. Beyond the digital shareability of the glam cam and Charlotte’s content, model and Tilbury muse Jourdan Dunn flew in to film her own bespoke beauty journey for her followers.”
The campaign drove a 700% year-on-year increase in Charlotte Tilbury sales, while the wider cosmetics category saw a 36% uplift, according to QDF.
From sales channel to global customer acquisition platform
Beyond immediate sales, travel retail is being positioned as a platform for customer recruitment and long-term brand engagement. For Mecca, Sydney Airport’s T1, which handled more than 17 million passengers in 2025, offers access to international consumers who may be encountering the retailer for the first time. The store is also a testing ground for future expansion, allowing Mecca to assess how travelers respond to its assortment, services and format.
Established travel retailers are also rethinking how they work with brands. At Gebr. Heinemann, Hoffmann sees closer collaboration and greater agility as essential to reaching new consumers. The retailer is adopting a test-and-learn approach at Düsseldorf, Hamburg and Berlin airports, piloting new products, brands and concepts before scaling successful ideas elsewhere.
The relationship between retailers and brands is consequently becoming more collaborative and data-driven, with success measured through both immediate sales and longer-term brand value.
QDF is taking this a step further by leveraging passenger insights across the wider Qatar Airways Group ecosystem. Rather than focusing solely on individual transactions, its conversations with brand partners center on which customer groups they want to reach and how to engage them throughout their journey.
“And while we always aim to drive conversion, the success metrics of our activations or pop-ups extend beyond the financial, into a space where brand affinity with customers can be built,” says Musleh.
Yet measuring that longer-term value remains a challenge. While airport retailers can track sales and engagement, establishing how an initial encounter translates into future purchases or lasting loyalty is more complex.
For Puig, the opportunity lies in recognizing that consumers don’t experience brands through isolated retail channels. Their relationship with a brand may begin online, develop through an airport experience and continue long after they return home. This calls for a more connected approach to product launches, consumer engagement and the investment brands make in travel retail.
“We don’t see travel retail as a channel; we see it as a moment in the consumer journey,” says Puig’s Grant.
Q&A with Matthew Growdon, president – Asia-Pacific Region and Travel Retail Worldwide, The Estée Lauder Companies
After the pandemic hurt its global travel retail business, The Estée Lauder Companies restructured its operations, diversifying beyond Chinese travelers and deploying more of its fragrance portfolio. Matthew Growdon, who oversees travel retail alongside the group’s Asia-Pacific business, explains how its Beauty Reimagined strategy is changing the way it approaches the channel — and where he sees the next growth opportunities.
Vogue: How has Estée Lauder reshaped its approach to travel retail, and how much of the business’s recovery can be attributed to those changes?
Matthew Growdon: The disruptions during and after Covid were a catalyst for us to really change the way we approach [not only] the channel, but pretty much the whole company.
One of the biggest changes has been becoming more consumer-centric. We looked at our organization and asked: is this the right structure for us? Do we have enough resources and capabilities where they can really make an impact? That led to a complete reset. Our teams are now much closer to the consumer and to our retail partners.
Before Covid, there was such a strong focus on traveling Chinese consumers. Whether you were at Heathrow or on the West Coast of the US, the assortment and communication were geared towards that consumer, primarily in skincare. We’ve had to rethink that.
We’re moving away from the cookie-cutter approach of leading with the same brand in every location. If Tom Ford is the dominant brand in a particular market, then that’s the brand we lead with. It sounds obvious, but it’s about being much more in tune with what consumers actually want.

How has that changed the brands you’re prioritizing in travel retail?
We’ve got more than 20 brands in our portfolio across fragrance, makeup, skincare, and haircare. But the reality is that we hadn’t really put the distribution footprint in place for some of them.
Artisanal fragrance has been doing extremely well over the past five years. We’re talking about brands like Le Labo, Kilian Paris, and even Jo Malone London, which is already well established, but wasn’t necessarily present at the right scale or in the right locations.

About 80% of the category mix in the West is fragrance, whereas historically around 70% in the East has been skincare. We had been leading globally with skincare brands such as Estée Lauder and La Mer. The growth in niche and luxury fragrance gives us an opportunity to deploy more of our portfolio in both regions.
At the other end of the market, we’re expanding The Ordinary. It’s hugely successful domestically, particularly with younger consumers, but historically wasn’t widely available in travel retail. We’ve launched with a couple of European partners, seen extremely strong initial sales, and are expanding distribution. It was one of the most requested brands from our retail partners at the recent Tax Free World Exhibition in Cannes.
So there’s this interesting bifurcation: younger consumers looking for accessible brands, and then these very expensive, artisanal fragrance brands are doing incredibly well.
Where do you see the biggest opportunities for growth?
China remains incredibly important. We’re seeing increasingly good numbers from Hainan and have just opened a new distribution center there. But we’re diversifying so we’re never overly reliant on one brand, consumer, or channel.
Japan has been one of the fastest-growing duty-free markets over the past five years, helped by tourism. In South Korea, we’re seeing strong retail growth again at Incheon Airport, although downtown duty-free is recovering more slowly.
The West is a significant opportunity because we’ve historically had lower market share and haven’t deployed our full fragrance portfolio. We’re expanding across Central Europe, the Middle East and North America, including new locations in Miami and Washington Dulles. India also offers tremendous potential, with significant investment in airport infrastructure. It’s a different category mix, with strong makeup and fragrance opportunities alongside more entry-level skincare.
When you combine the locations with the brands we haven’t yet fully deployed, it becomes a real multiplier for growth.
K-beauty and local challenger brands are attracting growing attention from international travelers. How is that changing the competitive landscape for Estée Lauder?
Korea is probably one of the most interesting beauty markets right now. You’ve got this whole phenomenon around K-beauty, K-pop, and K-drama. We’re seeing a huge influx of tourism from across Asia, as well as growing interest from Western travelers. And K-beauty brands bring a tremendous amount of innovation to the market, very rapidly. It’s actually good competition because it gets people excited about beauty. We have Dr.Jart+ in our portfolio, and The Ordinary is also doing well in Korea, alongside our luxury brands.
It’s not just Korea, either. There’s a tremendous amount happening in J-beauty, C-beauty, and now India too. We’ve recently concluded the acquisition of Forest Essentials, an Indian brand that we see potential to bring into travel retail, including as a showcase for the Indian diaspora traveling around the world.
So, in many ways, these trends open up opportunities for us.
What needs to change across the wider industry for travel retail to convert more passengers into shoppers?
I think the big opportunity is better coordination between airport authorities, retailers and brands.
Look at what consumers experience in the domestic market. You’ve got these beautiful boutiques, incredible shopping malls, specialist retailers like Sephora where you can discover all these little brands. That’s the standard. Why should travel retail be a stripped-down version of that?
We’re already working with partners on concepts for JFK’s new Terminal 1, including a unique New York theme across a range of our brands. It’s going to be very luxe and very much in keeping with the city.
I think the more the industry can work together and allow brands to express themselves creatively, the better it will be for everybody.
We cannot take the consumer for granted. Just because they’re traveling through an airport doesn’t mean they’re going to buy something. We have to understand what we’re competing with and come up with an even better proposition.
The dream would be for duty-free to offer the best shopping experience, the best service — somewhere people actually come to the airport early because they want to spend more time there. Not just somewhere they happen to pass through.